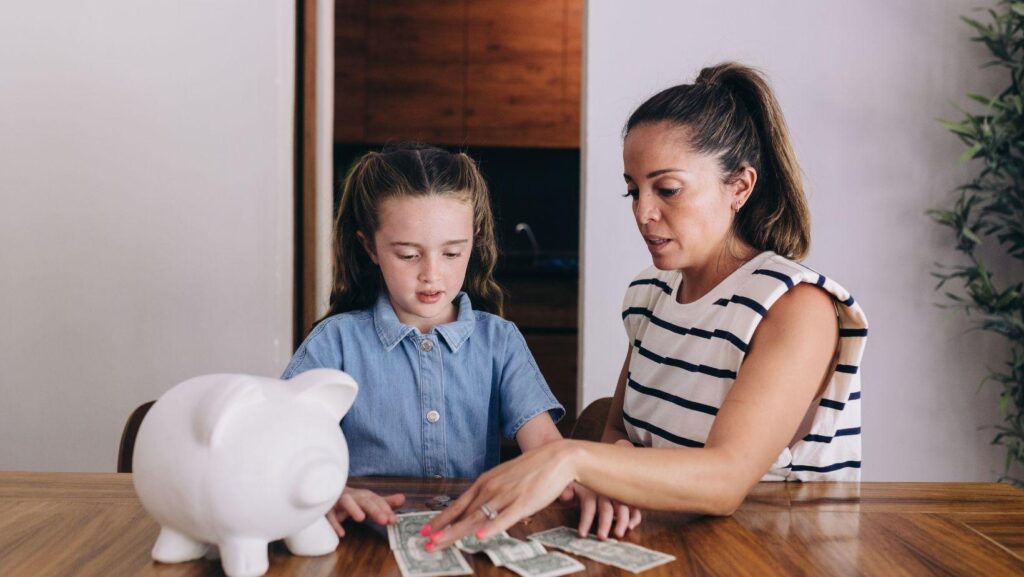
People have different views on single parenthood, but one thing everyone can agree on is that it comes with serious money management challenges. Most single parents will have one reliable source of income to draw from, which means every financial decision tends to carry more weight. Even when incomes are high and multiple income streams are present, single parents may still have to contend with balancing immediate needs with future goals.
Building stable finances in these circumstances may be difficult, but small, consistent actions can nudge your finances in the right direction. Follow these tips to better manage your finances as a solo parent.
1. Get a Clear View of Your Cash Flow
Everything starts with tracking your income sources and regular expenses. More general categories like groceries, utilities, school costs, and transportation should be broken down so that you know where comfortable adjustments can be made. Even a simple weekly check-in on your spending should help you stay within budget and avoid surprises.
2. Use Credit With a Clear Purpose
There may be moments when additional funds are necessary, such as covering specific medical costs, school fees, or urgent home repairs. In situations like these, access to a bank loan or revolving credit line can be a good thing to have. However, access to credit can sometimes cause irresponsible usage, simply because the option to borrow exists.
For that reason, single parents also need to be careful about where they borrow. Choosing a regulated financial institution and options with transparent fees, flexible loan amounts, and reasonable repayment periods can ensure that any borrowing remains sustainable. In particular, leading digital bank Maya offers Maya Personal Loan and Maya Easy Credit. These offer Php 400,000 and Php 50,000 loanable amounts, respectively, which can cover everything from a large hospital bill or an urgent appliance repair.
3. Learn to Effectively Separate Needs From Wants
When you want the best for your child, the line between essential and non-essential spending can become blurred. Even so, being intentional about your priorities goes a long way in keeping your budget in order. Focus first on necessities like food, housing, savings, healthcare, and education, then allocate what’s left for discretionary expenses. This approach keeps your finances grounded even during tighter months.
4. Build a Starter Emergency Fund ASAP
When money is tight, it’s sometimes hard to justify creating an emergency fund. However, in most cases, you don’t need to contribute a large sum right away. What matters is consistency. Over time, a monthly contribution into a high-yield savings account can compound, reducing your financial risks from minor emergencies.
5. Plan for Your Child’s Future Early
Similarly, you’ll want to create room in your budget for your child’s future education. The cost of quality education keeps rising year after year, making it one of the most profound long-term expenses you’ll need to deal with as a solo parent. Setting aside money early, even in small amounts, can help ease the financial pressure later on.
As with your emergency fund, consider opening a dedicated savings account for your child’s needs so the funds remain separate from your daily budget. This can make it easier to track your progress and stay committed to your goal. You can also consider purchasing an education plan to accelerate the growth of your child’s college funds.
6. Commit to Consistent Bill Payments When Possible
Keeping up with due dates can be challenging when you’re juggling multiple responsibilities. If your bank app allows it, automate your bill payments so you don’t incur any penalties from missed payments. Alternatively, you can set calendar reminders on your phone to stay on top of your obligations. Aside from keeping your budget safe from penalties, this consistency should improve your eligibility for better financial products in the future.
7. Protect Yourself With Basic Insurance
You may already have insurance through your employment, but it may be a good idea to invest in additional basic health or life insurance so that you have an independent safety net. While this may feel like an added expense, it can prevent an unstoppable cascade of financial setbacks down the line.
8. Look for Sustainable Ways to Increase Your Income
Exploring side opportunities, such as freelance work, online selling, or part-time roles, may give you extra breathing room in your budget, helping cover recurring costs or accelerate your savings goals. Ideally, this opportunity should be something that could be paused so that you can free up time in your schedule to spend with your child.
9. Keep Your Plans Flexible
Your financial situation will undoubtedly evolve as your child grows and your income streams change. A quarterly or even annual review can help you see if your initial budget is still workable. Given that expenses will increase over time, these review periods are often necessary to keep your plan realistic.
Staying Grounded While Planning Ahead
If nothing else, taking care of finances as a solo parent is a character-building exercise. Things will be difficult, but the careful planning and discipline that you learn often bleeds into other areas of life, leading to better things in the future. Find the support you need and, soon enough, you can ensure lasting financial security for your family.